Questions
Buying abroad, answered.
The questions our clients ask most about buying in Dubai, Greece and the United States — answered clearly.
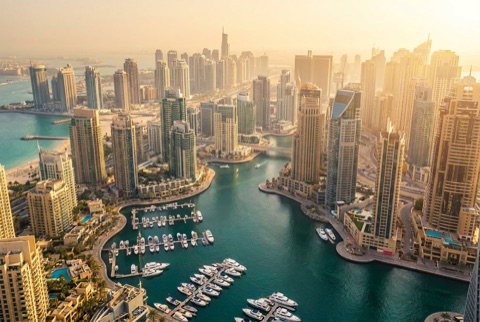
Yes. Since Dubai's landmark Freehold Law (Law No. 7 of 2002), foreign nationals of any citizenship can buy, own, sell and pass on property in Dubai's designated freehold areas. You do not need to be a UAE resident, you do not need a local sponsor or partner, and there is no requirement to live in the country to hold title. Ownership is registered directly in your own name with the Dubai Land Department (DLD), and the title deed is issued to you as the sole legal owner.
Foreign buyers enjoy the same purchase framework and the same headline costs as UAE and GCC nationals — there is no surcharge or additional transfer tax applied simply because you are an overseas investor. There is also no cap on the number of properties a foreigner may own, and no minimum purchase price imposed by the government (though lenders and the Golden Visa programme have their own thresholds, which we cover separately).
The one meaningful restriction is geographic rather than personal: foreign freehold ownership is limited to Dubai's designated freehold zones, which today number more than sixty communities and include virtually all of the prime coastline and investment districts. Older central neighbourhoods that fall outside these zones are reserved for UAE and GCC nationals. In practice, almost every property an international buyer would realistically consider — from a Marina apartment to a Palm Jumeirah villa — sits comfortably within freehold territory.
Freehold ownership gives you complete, indefinite title to both the property and the land it stands on. You can sell it on the open market whenever you wish, mortgage it, renovate it within community rules, and bequeath it to your heirs — all without needing permission from a landlord or master authority, and with no ground rent. This is the form of ownership that has made Dubai so attractive to international investors, and it is registered directly with the Dubai Land Department under your name.
Leasehold, by contrast, grants the right to use a property for a fixed term — typically up to 99 years — after which ownership reverts to the underlying freeholder. Leasehold arrangements exist mainly in Dubai's older, central districts that are not designated for foreign freehold ownership, such as parts of Deira, Bur Dubai and the original Jumeirah neighbourhood. For an international buyer focused on long-term security and resale value, freehold is almost always the preferred route.
Foreigners can buy freehold in more than sixty designated communities. These include the entire prime coastline and the districts most investors care about: Dubai Marina, Palm Jumeirah, Downtown Dubai, Business Bay, Bluewaters Island, Emaar Beachfront, Dubai Creek Harbour, Jumeirah Beach Residence (JBR) and Dubai Hills Estate, among many others. A useful point of confusion to clear up: the original low-rise Jumeirah district is largely leasehold for foreigners, but the similarly named JBR, Jumeirah Lake Towers, Jumeirah Village Circle and Jumeirah Islands are all fully freehold.
The single largest cost on top of the purchase price is the Dubai Land Department (DLD) transfer fee of 4% of the property value. While the law nominally splits this 2% to the buyer and 2% to the seller, in market practice the buyer almost always pays the full 4%. This fee is what secures registration of the property into your name and the issuance of your title deed.
Beyond the DLD fee, you should budget for a handful of transaction charges: a registration and title-deed fee of roughly AED 2,000 for properties under AED 500,000 or AED 4,000 for those above, plus 5% VAT on that fee; a registration trustee office charge; and a small administrative and knowledge fee. If you use a broker, agency commission is customarily 2% of the purchase price plus VAT. If you buy with a mortgage, add a mortgage registration fee of 0.25% of the loan amount plus bank arrangement and valuation fees.
Taken together, an international buyer should plan for total closing costs in the region of 5% to 9% of the purchase price, depending on whether the deal involves a mortgage and a broker. It is worth noting that these are largely one-off transaction costs. Dubai levies no annual property tax and no capital gains tax, so once the deal completes your ongoing obligations are limited chiefly to service and community charges.
The DLD transfer fee is the Dubai Land Department's charge for officially transferring and registering ownership of a property into your name. It is calculated at 4% of the agreed purchase price (or the DLD's assessed value, whichever the department applies) and is the mechanism by which your ownership becomes a matter of public legal record. Payment of this fee is what triggers the issuance of your title deed, so the transfer is not considered complete until it is settled.
Legally the fee is shared equally between buyer and seller at 2% each, but the long-standing custom in Dubai is that the buyer absorbs the entire 4%. This is simply how the market has settled, and it is reflected in most standard sale contracts. It is, however, a point that can occasionally be negotiated — in a softer market or on a motivated sale, a seller may agree to contribute, so it is always worth raising during negotiations.
The 4% rate is flat and uniform: it does not change with the property's location, type or price band, and foreign buyers pay exactly the same rate as residents and nationals. The fee is typically due at the point of transfer at the DLD or a registration trustee office, and should be settled promptly to avoid penalties. Because it is a one-time cost rather than a recurring tax, it is best viewed as part of your acquisition budget rather than an ongoing liability.
Off-plan means buying a property still under construction directly from a developer, usually paying in instalments across the build. Ready property means a completed unit you can inspect, take possession of and register immediately. Both are entirely viable for international buyers, and the right choice depends on your timeline, your appetite for phased payments, and whether you want an asset you can use or resell straight away.
Off-plan is popular for good reasons: entry prices are typically lower than comparable finished stock, developers offer extended payment plans that spread the cost over the construction period and sometimes beyond handover, and there is scope for capital appreciation between launch and completion as the project and surrounding community mature. Off-plan has consistently dominated Dubai transaction volumes in recent quarters. The trade-offs are that you wait for completion, you rely on the developer delivering on time and to specification, and your money is committed before you can physically inspect the finished home.
Ready property offers certainty and immediacy. You see exactly what you are buying, you can complete due diligence on the actual unit and building, and ownership — with title deed in hand — transfers on completion of the sale. Prices in prime, supply-constrained locations tend to hold value well. For buyers who want to move in, or who prefer to avoid construction risk entirely, ready stock is the more conservative path. A sound advisory conversation usually comes down to weighing the lower entry cost and upside of off-plan against the security and speed of ready.
Dubai's off-plan market is underpinned by a mandatory escrow system regulated by the DLD and supervised by RERA (the Real Estate Regulatory Agency). Under Law No. 8 of 2007, every off-plan project in a freehold area must have a dedicated, project-specific escrow account. When you pay instalments, your money goes into that escrow account — not the developer's general funds — and can only be spent on the construction of that particular project.
Crucially, funds are released to the developer in stages tied to verified construction progress, not to the calendar. An independent, DLD-approved engineering consultant inspects the site and certifies that a given stage has been reached; only then does the bank release the corresponding tranche. Developers are also required to inject a meaningful share of construction cost upfront before they can sell, and to submit periodic progress and expenditure reports. This milestone-linked structure is the single most important protection an off-plan buyer has, because it directly limits the risk of your money disappearing into a stalled project.
Oqood is the interim registration certificate for off-plan purchases. Because the property does not physically exist yet, you cannot receive a title deed at the point of purchase; instead, the DLD records your contract on the Oqood system, giving you an officially registered, legally recognised claim to the unit during construction. When the project completes and the property is handed over, the Oqood registration converts into a full title deed in your name. Verifying that your purchase is properly registered on Oqood is an essential due-diligence step in any off-plan deal.
One of the most attractive features of buying off-plan in Dubai is the developer payment plan, which lets you spread the purchase price over the construction period rather than paying in full upfront. A typical structure begins with a booking deposit — often between 5% and 20% of the price — followed by a series of instalments paid at defined milestones as the building progresses, with a final balance due on handover.
By regulation, these payment schedules must be linked to genuine construction progress and aligned with the escrow disbursement framework, so instalments generally fall due as verified stages of the build are completed. Many developers also offer post-handover payment plans, where a portion of the price is paid in instalments over one, two or several years after you have taken possession of the property. These arrangements can make a purchase considerably more accessible without the need for a mortgage.
For an international buyer, the appeal is twofold: you commit less capital at the outset, and you can often secure a prime unit at launch pricing while paying it down gradually. That said, payment plans are contractual commitments, so it is important to understand the schedule fully, confirm how instalments relate to construction milestones, and ensure the plan is documented in your sale and purchase agreement. A clear-eyed review of the payment terms is a core part of the advisory work we do before you commit.
The UAE Golden Visa is a ten-year, renewable residency visa that you can qualify for by investing in Dubai real estate. The property threshold is AED 2 million (roughly USD 545,000) in value. You can meet this with a single property or a combination of properties whose total qualifying value reaches AED 2 million, and both ready and off-plan properties from approved developers are eligible.
A significant recent change has widened access to the programme. The previous requirement for a large minimum down payment on mortgaged properties has been removed, meaning that mortgaged and off-plan purchases can now qualify provided the Dubai Land Department's valuation of the property reaches or exceeds AED 2 million. Eligibility is assessed against the DLD's current valuation rather than only the price on the deed, so a proper valuation is central to a Golden Visa application.
The benefits are substantial and are a major reason international buyers choose Dubai. The visa runs for ten years and renews as long as you retain the qualifying property. It is self-sponsored, so you need no employer or local sponsor, and it allows you to sponsor your spouse, children and parents under the same application. Unlike ordinary UAE residence visas, it is not cancelled by long absences from the country, giving genuinely flexible residency. In effect, a single qualifying property purchase secures both a long-term investment and long-term residency for your family.
Yes, a number of UAE banks lend to non-resident foreign buyers, though on more conservative terms than for residents. The key figure is the loan-to-value ratio (LTV). For non-residents, the maximum LTV typically sits around 50% to 65%, meaning you should expect to fund a down payment of roughly 35% to 50% of the property value from your own resources. Ready properties under AED 5 million tend to attract the more generous end of that range, higher-value and off-plan properties the more conservative end.
Interest rates for non-residents generally run in the region of 5% to 6.5%, and can be a little higher than the rates offered to residents; with a strong income profile, a large down payment and good credit history, more competitive rates are achievable. Banks commonly look for a minimum monthly income in the order of AED 15,000 or its foreign-currency equivalent, keep your total debt servicing within about half of your income, and offer terms of roughly 20 to 25 years. Financing is only available on properties in freehold areas.
Because criteria, rates and appetite vary meaningfully between lenders, it is well worth securing a mortgage pre-approval before you commit to a property. Pre-approval confirms your budget, strengthens your negotiating position, and smooths the transaction timeline. Many international buyers, however, choose to purchase in cash or via developer payment plans and avoid financing altogether — a decision that depends on your wider portfolio and how you wish to deploy capital, and one we are glad to talk through.
Ownership in Dubai is recorded through a centralised, government-run register maintained by the Dubai Land Department. When a purchase completes, the DLD issues an electronic title deed — the definitive legal document proving your ownership. It records the owner's name, the property details, the plot and unit information and the ownership type. Because registration is centralised and digital, ownership records are secure, transparent and straightforward to verify.
For a ready property, the title deed is issued to you at the point of transfer, once the purchase price, the DLD transfer fee and associated charges are settled at a registration trustee office. For an off-plan purchase the sequence differs: during construction your interest is recorded on the Oqood interim registration system, and the full title deed is issued upon completion and handover of the finished unit.
This robust registration framework is one of the pillars of confidence in Dubai's property market. It means your ownership is not dependent on a developer's or a third party's records but on an official state register, and that any future sale, mortgage or inheritance transfer is processed through the same trusted system. As part of due diligence, we always confirm that the seller's title is clean and properly registered before a transaction proceeds.
No. Dubai does not levy an annual property tax on residential real estate, and it imposes no capital gains tax when you sell. This is one of the defining advantages of investing in Dubai property and a major reason it attracts international buyers who are used to recurring property taxes and gains taxes in their home countries. Once you own, there is no yearly tax bill from the government tied to simply holding the asset.
This does not mean ownership is entirely cost-free. Owners pay annual service and community charges to maintain the building and shared facilities, and these are a genuine ongoing expense to factor in. There are also the one-off transaction costs on purchase, chiefly the 4% DLD transfer fee. But there is no equivalent of the annual council tax, property tax or land tax that many overseas buyers are accustomed to.
The absence of capital gains tax is particularly meaningful for investors focused on appreciation. When you sell a property that has grown in value, the uplift is not diminished by a local gains tax, so the full appreciation accrues to you subject only to transaction costs. Buyers should of course consider their own home-country tax position, since your country of tax residence may still have rules on foreign-held assets — but from the Dubai side, the ownership tax environment is exceptionally light.
The process is well established and, for a ready property, can move quickly — often completing within a few weeks. It begins with defining your objectives and budget, then identifying and viewing suitable properties. Once you settle on one, you negotiate the price and terms and sign a Memorandum of Understanding (Form F), the standard sale agreement, usually accompanied by a deposit of around 10% held by the agent or a trustee.
If the property carries an existing mortgage, the seller clears it; in all cases the seller obtains a No Objection Certificate (NOC) from the developer confirming that service charges are settled and there is no impediment to transfer. Buyer and seller then meet at a DLD-approved registration trustee office to complete the transfer, where the purchase price is paid (typically by manager's cheque), the 4% DLD fee and associated charges are settled, and a new title deed is issued in your name. If you are financing the purchase, your mortgage is registered at the same stage.
For a ready cash purchase, this end-to-end journey commonly takes two to six weeks. Off-plan purchases follow a different rhythm — you reserve the unit, sign the sale and purchase agreement, and the property is registered on Oqood, with the payment plan running across the construction period and the title deed issued at handover. Throughout either path, a good advisory house manages the due diligence, coordinates with the DLD and trustee, and ensures each step is documented correctly, which is where much of the real value lies for an overseas buyer.
Yes. It is entirely possible to complete a Dubai property purchase without being physically present, and many international investors do exactly that. The usual mechanism is a Power of Attorney (POA), a legal document by which you authorise a trusted representative — often a lawyer or a specialist within your advisory house — to act on your behalf in signing documents, settling payments and completing registration with the Dubai Land Department.
For the POA to be valid in the UAE, it generally needs to be notarised and legalised (or apostilled) in your home country and then attested for use in Dubai, and where it is not in Arabic it will need a legal translation. Preparing this correctly and in advance is the key to a smooth remote transaction, and it is something we routinely coordinate for overseas clients so that the paperwork is in order before it is needed.
With a properly executed POA in place, your representative can handle the entire transfer at the registration trustee office and secure your title deed while you remain abroad. Modern digital channels also make it easier than ever to review documents, transfer funds internationally and stay fully informed at each step. Remote purchasing does place a premium on trust and thorough due diligence, so working with a reputable, transparent advisor who represents your interests — not the seller's — is especially important when you are buying from a distance.
Thorough due diligence is the foundation of a secure purchase, and Dubai's regulatory framework gives you strong tools to carry it out. For any purchase, you should confirm the seller's title is clean and properly registered with the Dubai Land Department, check that all service charges are settled, and ensure there are no undisclosed mortgages or encumbrances on the property. A No Objection Certificate from the developer is part of this confirmation on resales.
When buying off-plan, verifying the developer and the project is paramount. You should confirm that the developer is licensed and registered with RERA, that the specific project is officially registered, and that it has a dedicated escrow account into which your payments will be deposited. Checking the developer's track record — previous projects, delivery history and reputation for handing over on time and to specification — is equally important, since the credibility of the developer is the best predictor of a smooth off-plan experience.
Much of this information is verifiable through official DLD and RERA channels, which is a genuine strength of the Dubai market compared with many jurisdictions. That said, interpreting the paperwork, spotting red flags and confirming that the escrow and Oqood registrations are properly in place is where professional guidance earns its keep. A reputable advisory house conducts this verification on your behalf, so you can commit capital with confidence rather than hoping the documentation stacks up.
Handover is the moment a completed property is delivered to you by the developer, marking the transition from a project under construction to a home you own outright. At this stage the developer notifies you that the unit is ready, you settle any final instalment due on completion, and the property is registered to you with a full title deed issued by the Dubai Land Department. It is the culmination of an off-plan purchase and, understandably, an exciting milestone.
Snagging is the careful inspection you carry out before you formally accept the property. It involves going through the unit in detail — checking finishes, fittings, plumbing, electrics, air conditioning, doors, windows and the general quality of the build — and compiling a list of any defects or unfinished items, known as the snag list. This list is submitted to the developer, who is responsible for rectifying the issues before or shortly after handover. Many buyers engage a professional snagging company to conduct this inspection thoroughly and objectively.
Snagging matters because it is your opportunity to hold the developer to the standard promised in your contract while there is still clear leverage to do so. Reputable developers also provide a defects liability or warranty period after handover, during which they remain responsible for putting right structural and workmanship issues. Approaching handover methodically — inspecting before you sign off, documenting everything, and understanding your warranty rights — protects both your enjoyment of the property and its long-term value.
Selling a property in Dubai follows a clear, regulated process that mirrors the purchase. Once you agree a sale with a buyer, the two parties sign a Memorandum of Understanding (Form F) setting out the price and terms, typically accompanied by a deposit. If there is a mortgage on the property it must be settled, and both parties then progress towards transfer at a DLD registration trustee office, where the buyer's payment is exchanged and a new title deed is issued in the buyer's name.
A central step in any resale is obtaining the No Objection Certificate (NOC) from the developer or master community. The NOC confirms that all service charges and community fees are paid up to date and that the developer has no objection to the transfer of ownership. The DLD will not complete the transfer without it, so securing the NOC — which usually involves clearing any outstanding charges and paying a fee to the developer — is an essential part of preparing a property for sale.
Because Dubai imposes no capital gains tax, the appreciation your property has earned accrues to you on sale, subject only to transaction costs. The absence of a gains tax, combined with a liquid and internationally active buyer pool in prime areas, is a large part of what makes Dubai attractive for investors focused on capital growth and resale. A capable advisor manages the sale process end to end — pricing, marketing, buyer qualification, NOC and transfer — to achieve the strongest result while keeping the transaction clean and compliant.
Dubai property has delivered strong capital growth in recent years, and the outlook for the period ahead remains constructive, though the market is maturing into a more selective phase. Independent research houses forecast continued citywide appreciation, with some projecting high single-digit to low double-digit growth in value and villas expected to outperform apartments. Consensus expectations broadly sit in a healthy positive range, underpinned by sustained population growth, investor demand and Dubai's standing as a global hub.
Performance varies meaningfully by location and property type, which is where advisory judgement matters. Prime, supply-constrained coastline addresses such as Palm Jumeirah and Downtown Dubai continue to command premium pricing because scarcity supports value, while certain emerging communities offer stronger percentage growth potential as their infrastructure completes and they mature. Off-plan has continued to account for the majority of transactions, reflecting confidence in future delivery and appreciation between launch and completion.
For an investor, the appeal of Dubai's appreciation story is amplified by the tax environment: with no annual property tax and no capital gains tax, the growth in your asset's value is not eroded by local taxation. As with any market, appreciation is never guaranteed and prices move in cycles, so the discipline lies in choosing the right asset in the right location at the right entry point. That is precisely the analysis we bring to every client — aligning the purchase with your investment horizon and appetite rather than chasing headline numbers.
Foreign buyers in Dubai can purchase apartments, villas, townhouses, penthouses and serviced residences across the designated freehold communities. Apartments dominate the high-rise waterfront districts and appeal to investors seeking liquid, sought-after stock, while villas and townhouses in master-planned communities attract families and those seeking space, privacy and land — a segment that has shown particularly strong value growth.
The Dubai coastline is home to the market's most iconic addresses. Dubai Marina is one of the most established and liquid districts, a dense waterfront community of towers that trades actively and remains a perennial favourite with international investors. Palm Jumeirah, the emblematic man-made island, commands the highest absolute prices and offers beachfront villas and premium apartments with a scarcity that supports enduring value. Jumeirah Beach Residence (JBR) offers a vibrant beachfront lifestyle, while newer waterfront destinations such as Emaar Beachfront, Bluewaters Island and Dubai Creek Harbour have rapidly become desirable prime locations.
Beyond the immediate coast, communities such as Downtown Dubai, Business Bay and Dubai Hills Estate round out the roster of prime districts favoured by overseas buyers. The right choice depends on your goals — a liquid, easily resold apartment; a trophy beachfront villa; or an emerging community with room to grow. As a coastline-focused advisory house, our role is to match you with the address and property type that genuinely fit your objectives, drawing on close knowledge of how each community behaves in terms of value and resale demand.
Service charges are the annual fees owners pay to cover the upkeep of their building and its shared facilities — things like maintenance of common areas, security, cleaning, landscaping, lifts, swimming pools, gyms and the master community's infrastructure. They are the principal ongoing cost of owning property in Dubai and are levied because these shared amenities require continuous funding to keep the community well maintained and, in turn, to protect property values.
Charges are calculated per square foot of your property and vary considerably by location, building age and the level of amenities on offer. A high-amenity tower on the prime coastline with extensive facilities will carry higher per-square-foot charges than a simpler building, and villa communities differ again. Because these fees are a real and recurring expense, they should always be factored into your purchase analysis — both for budgeting and because they affect the net return on an investment property.
Dubai's regulator oversees service-charge structures to promote transparency, and approved rates are a matter of record, so you can verify the charge for a given building before you buy. As part of due diligence, we confirm the applicable service charges for any property under consideration and check that the seller's charges are settled — the latter being a prerequisite for the No Objection Certificate needed to transfer ownership. Understanding these charges upfront ensures there are no surprises after completion.
Inheritance is a question every foreign owner in Dubai should address deliberately. In the absence of a registered will, a deceased owner's UAE assets can, by default, fall to be dealt with under UAE federal inheritance principles, which may distribute an estate differently from how an international owner would wish. For non-Muslim expatriates in particular, this can produce outcomes that do not reflect their intentions, so proactive estate planning is strongly advised.
The solution most international owners use is a DIFC will, registered through the Dubai International Financial Centre's Wills and Probate Registry. The DIFC operates a common-law-based framework designed specifically for non-Muslims, and a registered will there allows you to direct exactly how your Dubai property and other UAE assets should pass on. It provides testamentary freedom, a clear and comparatively fast probate route through the DIFC Courts, and certainty for your heirs — avoiding the delays and unpredictability that can arise without one.
A few practical points are worth noting. Joint tenancy with automatic survivorship, familiar to UK and US owners, does not apply under UAE property law, so co-owning spouses or partners should each register their own will (or mirror wills) rather than assume a share passes automatically. Registration is a well-defined process with modest cost relative to the security it provides. While a DIFC will is a legal matter for a qualified professional to draft, we routinely flag its importance to overseas buyers and can point you to the right specialists, because protecting your investment for your family is part of buying well.
Property in Dubai is transacted in UAE dirhams (AED). For international buyers, the most reassuring feature of the currency is that the dirham has long been pegged to the US dollar at a fixed rate of approximately 3.6725 AED to 1 USD. This peg has been maintained consistently for decades and is a cornerstone of the UAE's monetary stability, which in turn supports confidence in dirham-denominated assets such as real estate.
For a buyer whose wealth is held in or referenced to US dollars, the peg effectively removes exchange-rate risk between the dollar and the dirham: the value of your Dubai property in dollar terms is not subject to the currency swings that can affect real estate in floating-currency markets. This stability is one of the quieter but genuinely important reasons that dollar-based international investors find Dubai an attractive and predictable place to hold property.
Buyers who hold their wealth in other currencies — pounds, euros, or others — should of course consider the exchange rate between their home currency and the dollar-linked dirham at the time of purchase and any future sale, since that relationship still moves. Timing a transfer and, where appropriate, using foreign-exchange tools to manage the conversion can make a meaningful difference on a large purchase. It is a practical consideration we are happy to help you think through as part of planning the transaction.
Dubai has become one of the world's most compelling destinations for international property investment, and the reasons are structural rather than seasonal. Foreigners can own freehold property outright in their own name; there is no annual property tax and no capital gains tax; the currency is stably pegged to the US dollar; and the market operates within a transparent, well-regulated framework overseen by the Dubai Land Department and RERA, with mandatory escrow protection for off-plan buyers. Few global markets combine full foreign ownership, this light tax environment and this level of regulatory protection.
The investment case is reinforced by the city itself: sustained population and economic growth, world-class infrastructure, safety, connectivity as a global hub, and a lifestyle that continues to draw people and capital from around the world. Prime coastline addresses in particular benefit from genuine scarcity, which supports both value retention and resale demand. For investors focused on capital appreciation, the combination of a growing market and the absence of a gains tax means growth in value is retained in full, subject only to transaction costs.
Layered on top is the residency dimension. A qualifying property investment of AED 2 million can secure a ten-year, renewable Golden Visa covering your family, giving Dubai an appeal that goes beyond the asset itself. Taken together — ownership security, tax efficiency, currency stability, regulatory protection, growth potential and a route to residency — these are the pillars on which we help international clients build a Dubai property position that is sound, well-chosen and aligned with their long-term goals.
Yes. Greece places no general restriction on foreign ownership of real estate, and buyers from the EU and beyond enjoy essentially the same purchase rights as Greek nationals. Whether you are American, British, from the Gulf, or elsewhere, you can acquire full freehold title to apartments, houses, villas and land, and hold that title indefinitely. This openness, combined with a maturing legal framework, is one of the reasons Greece has become a favoured destination for lifestyle buyers and long-term capital-appreciation investors alike.
There is one meaningful exception. In designated border regions and on certain frontier islands close to Turkey and other neighbours, non-EU nationals must obtain a permit from a decentralised administrative committee before completing a purchase. These zones include parts of the Dodecanese, the North Aegean islands, Crete, and areas near the northern land borders. The clearance is largely a formality for residential buyers, but it adds a step and some weeks to the timeline, so it must be identified early.
At Maris Estates we screen every prospective acquisition against these rules before you commit, so there are no surprises at the notary. For the vast majority of coastal and island properties our clients target, ownership is straightforward, secure, and fully protected under Greek and EU law.
The Greece Golden Visa is a residency-by-investment programme that grants a five-year, renewable residence permit to non-EU investors and their families in exchange for a qualifying real-estate purchase. It remains one of Europe's most popular such programmes, valued for the mobility it offers within the Schengen Area and for the fact that it does not require you to live in Greece to keep the permit.
Greece overhauled the thresholds in 2024, moving from a single €250,000 minimum to a tiered structure that took full effect on 31 August 2024. Today the minimum investment is €800,000 in the highest-demand zones, which include Attica (greater Athens), Thessaloniki, Mykonos, Santorini and the islands with a population above roughly 3,100 residents. In the rest of the country the minimum is €400,000. Both of these tiers require the investment to be made in a single property with a minimum surface area of 120 square metres.
A €250,000 route still exists but is now reserved for two special cases: the restoration of listed or protected buildings, and the conversion of commercial premises into residential use. These heritage and conversion projects are exempt from the 120-square-metre rule. Because the tiers turn on precise geography, population figures and property type, verifying which threshold applies to a specific asset is essential before you proceed, and it is an area where Maris Estates advises clients closely.
The Golden Visa is designed as a family programme. The main applicant can include a spouse or registered partner, dependent children up to the age of 21, and the parents of both spouses. This makes it an efficient way to secure European residency for a whole household through a single qualifying investment.
Holders and their families receive the right to reside in Greece and to travel visa-free within the Schengen Area for up to 90 days in any 180-day period. Crucially, there is no minimum-stay obligation to maintain the permit, which distinguishes Greece from several competing programmes and suits investors who want an EU foothold without relocating.
The permit is renewed every five years for as long as the qualifying property is retained. It confers residency rather than citizenship, and it does not by itself grant the right to work as an employee, though investors may hold company shares and run businesses. Those seeking eventual naturalisation follow a separate, longer path described elsewhere in these FAQs.
The process follows a clear sequence. After you identify a property and agree terms, your lawyer conducts legal due diligence on the title while a civil engineer or surveyor verifies the building's technical and planning status. In parallel, you obtain a Greek tax number (AFM) and, typically, a Greek bank account through which purchase funds are transferred. A preliminary agreement, often accompanied by a deposit of around 10 percent, secures the property while these checks are completed.
Once due diligence is clear, the transaction concludes with the signing of the final purchase deed before a Greek notary, who is a public official responsible for ensuring the deed is lawful and correctly executed. Both parties, or their attorneys acting under power of attorney, sign in the notary's presence, the balance of the price is paid, and the transfer tax is settled. The notary then confirms the transfer of ownership.
The final and essential step is registration of the new deed with the competent Land Registry or Cadastre office, which perfects your title against third parties. From an accepted offer to registered ownership, a straightforward resale typically takes six to twelve weeks. Maris Estates coordinates the lawyer, notary, engineer and banking steps so the timeline stays on track.
In Greece the notary (symvolaiografos) is a mandatory and central figure in every property transaction. Unlike in some common-law countries where a private conveyancer handles the paperwork, Greek law requires the final sale deed to be drafted and executed before a notary, who acts as an impartial public officer rather than as the representative of either buyer or seller.
The notary verifies the identities and legal capacity of the parties, confirms that the required tax and Cadastre documentation is in order, ensures the transfer tax has been paid, reads and formalises the deed, and issues certified copies. Because the notary's signature gives the deed its legal force, this step is the true moment of transfer.
Notary fees are broadly in the region of 1 to 1.5 percent of the property's value, plus VAT and minor disbursements. While the notary safeguards the legality of the deed itself, they do not represent your private interests or investigate the title in depth, which is precisely why an independent buyer's lawyer remains indispensable alongside them.
Yes. Every buyer, resident or not, must obtain an AFM, the nine-digit Greek tax identification number issued by the Independent Authority for Public Revenue (AADE). The AFM is a prerequisite for signing the notarial deed, registering the property, paying property taxes, and opening a Greek bank account, so it is one of the first practical steps in any purchase.
Non-residents can obtain an AFM either in person at the local tax office or, more commonly, remotely by authorising a Greek lawyer or accountant to apply on their behalf under a power of attorney. You will typically need a valid passport and proof of address; documents originating abroad may require an apostille and official translation.
Handled through a competent representative, the AFM is usually issued within one to three weeks. Because it underpins every subsequent stage, Maris Estates ensures clients secure their AFM early so the purchase can proceed without administrative delay.
Engaging an independent lawyer is strongly recommended and, in practice, effectively essential. Greek property law is document-intensive, and the lawyer's role is to protect your interests independently of the notary, the agent and the seller. Legal fees generally run from around 1 to 1.5 percent of the purchase price, sometimes with a minimum, and represent some of the best-value money you will spend on the transaction.
Due diligence begins with the title chain, confirming that the seller is the lawful owner and that the property is free of mortgages, liens, pre-notations, seizures or unresolved inheritance claims. The lawyer checks entries at the Land Registry and Cadastre, reviews prior deeds, and confirms there are no outstanding debts, such as unpaid ENFIA, that could attach to the property.
In parallel, a civil engineer verifies the building's legality: that the constructed footprint matches the approved permits, that no unauthorised additions exist, and that any past planning irregularities have been properly regularised. Only when both the legal and technical reviews are clean should you proceed to the final deed. This combined check is the single most important safeguard for a secure, appreciating investment.
Greece is completing a nationwide transition from the older Land Registry system (Ypothikofylakeio), organised around named owners, to the modern Hellenic Cadastre (Ktimatologio), a unified digital database organised around the property itself. The Cadastre maps precise boundaries and records ownership and legal rights parcel by parcel, giving each property a unique twelve-digit KAEK identifier.
This reform substantially improves the security and transparency of Greek real estate. The vast majority of ownership rights across the country have now been recorded, and in many areas the Cadastre is fully operational, allowing rights on a specific property to be verified digitally. Where the Cadastre is not yet finalised, transactions still proceed through the traditional Land Registry.
For a buyer, the practical point is that your lawyer must confirm the property's status in whichever system governs its location, and your new deed must be registered promptly after signing to perfect your title. Greece is also building an integrated digital property register linking Cadastre, tax and E9 declarations, further tightening the framework, so accurate registration matters more than ever.
For resale properties, the main acquisition cost is the property transfer tax, levied at 3 percent of the taxable value. A municipal surcharge of 3 percent is applied on top of that tax amount, bringing the effective total to approximately 3.09 percent. The tax is calculated on the higher of the declared purchase price and the property's official assessed value, and it is paid before the notarial deed is signed.
This transfer tax applies to resales and to new-build properties that fall under the VAT suspension regime, which currently covers the large majority of new stock. It is one of the more competitive acquisition taxes in Southern Europe, which supports Greece's appeal for buyers focused on long-term capital appreciation.
Because the tax is assessed on the higher of price or official value, it is important to understand the assessed value of a specific property in advance. Maris Estates and your lawyer confirm the exact figure so you can budget the transfer tax precisely before proceeding to signing.
Newly built properties sold by a developer are, in principle, subject to 24 percent VAT on the sale price rather than the transfer tax. That would make a brand-new home significantly more expensive to acquire than an equivalent resale. To support the construction market, however, Greece has operated a VAT suspension regime that allows developers to sell qualifying new homes outside VAT.
This suspension has been repeatedly extended and, under legislation passed in November 2025, now runs through 31 December 2026. Where it applies, a qualifying new-build sale attracts only the much lower transfer tax of around 3.09 percent instead of 24 percent VAT, a very substantial saving that materially improves the economics of buying new.
The suspension is not automatic for every property, so it must be confirmed for the specific unit and developer in question, and the framework can change when it comes up for renewal. Maris Estates verifies the VAT position on any new-build our clients consider, so the true acquisition cost is clear from the outset.
ENFIA is Greece's unified annual property tax, payable by anyone who owns real estate in the country on 1 January of each year. It is assessed by the tax authorities using the property's objective characteristics, including location, surface area, age, floor level, use and frontage, so two properties of similar price can carry different ENFIA bills depending on these factors.
The main charge is calculated on a per-square-metre basis that broadly ranges from around €2 to €16 per square metre for the principal tax band, with a supplementary charge applying to individuals whose total Greek real-estate value exceeds €500,000. For a typical holiday home or apartment, ENFIA is a modest annual cost rather than a major burden, and it can generally be paid in monthly instalments across the year.
Recent measures have introduced targeted reductions, including relief for main residences in smaller rural settlements. Because unpaid ENFIA can attach to a property and must be cleared before any future sale, your lawyer confirms that all prior-year ENFIA is settled as part of due diligence, and Maris Estates can help arrange ongoing compliance after purchase.
As a rule of thumb, budget roughly 8 to 12 percent on top of the purchase price for a resale to cover all transaction costs. The main components are the transfer tax of about 3.09 percent, notary fees of around 1 to 1.5 percent, legal fees of around 1 to 1.5 percent, and Land Registry or Cadastre registration fees of roughly 0.5 percent, plus VAT on the professional services.
If you engage a buying agent or advisory house, a fee typically in the region of 2 to 3 percent plus VAT may apply, and mortgage arrangement, valuation and translation or apostille costs add smaller amounts where relevant. For a new-build under the VAT suspension regime the structure is similar, since the low transfer tax replaces VAT.
These costs are one-off and predictable, and they are competitive by Southern European standards. Maris Estates provides a clear, itemised cost projection for any target property before you commit, so your total cash requirement, including taxes and professional fees, is fully understood in advance.
Yes, though financing is more conservative than for Greek residents. Major banks with international desks, including Alpha Bank, National Bank of Greece and Eurobank, lend to non-resident buyers. EU citizens can often borrow up to around 70 to 80 percent of value for a primary residence and somewhat less for a holiday home, while non-EU buyers are typically capped nearer 60 to 65 percent loan-to-value. Most foreign buyers should therefore plan to contribute at least 35 to 45 percent of the price in cash, plus costs.
Banks assess affordability carefully, generally expecting demonstrable international income, several months of bank statements, and evidence of assets, with monthly repayments kept within roughly 30 to 40 percent of income. Terms for overseas buyers commonly run up to around 15 years, and interest rates for non-residents in the current market broadly fall in the 4 to 5.5 percent range.
Because approval and valuation take time, financed purchases run a longer timeline than cash deals, and the loan offer should be arranged before you are contractually committed. Many of our clients buy in cash for speed and negotiating strength, but for those who prefer leverage, Maris Estates can introduce experienced non-resident lending desks.
Both routes can make excellent investments, and the right choice depends on your priorities. New-build and off-plan properties offer modern construction standards, better energy efficiency, warranties, and, where the VAT suspension applies, an acquisition tax of only around 3.09 percent rather than 24 percent VAT. They require less immediate renovation but can involve construction timelines and staged payments on off-plan purchases.
Resale properties, particularly well-located coastal and island homes, often offer established character, mature surroundings, and in some cases the potential to add value through renovation. The due diligence emphasis shifts toward verifying building legality and confirming that any past additions were properly permitted, since older Greek stock more frequently carries planning irregularities that must be regularised.
From a capital-appreciation standpoint, location and title quality matter more than the age of the building. Maris Estates evaluates each opportunity on its fundamentals, guiding clients toward the assets, whether new or resale, that offer the strongest prospects for secure ownership and long-term value growth.
Yes. An Energy Performance Certificate (EPC, known locally as PEA) is legally required for the transfer of most buildings in Greece and must be in place for the notarial deed. The certificate is issued by a licensed energy inspector, rates the property on an energy-efficiency scale, and is valid for ten years. On a purchase it is the seller's responsibility to provide it.
Beyond satisfying the legal requirement, the EPC is a useful signal of a property's condition and running costs. A strong rating points to lower energy bills and typically greater buyer appeal on future resale, whereas a poor rating may flag older systems, weaker insulation or renovation opportunities that could affect both comfort and value.
As part of coordinating a purchase, Maris Estates and your lawyer confirm that a valid EPC exists and factor its rating into the overall assessment of the property, so you understand both your legal position and the practical implications for long-term ownership.
Verifying planning legality is one of the most important safeguards when buying in Greece, especially for older houses, villas and rural properties. The core question is whether the building as it stands matches the permits and plans approved by the town-planning authority, and whether any extensions, conversions or auxiliary structures were lawfully authorised or properly regularised.
This review is carried out by a licensed civil engineer, who inspects the property, compares it against the official building file and topographic diagrams, and issues an engineer's certificate confirming that there are no unresolved arbitrary constructions. Where past irregularities exist, Greek law has provided regularisation mechanisms, but any outstanding issues must be settled before, or as a condition of, completing the purchase.
Skipping this step is a serious risk, as unpermitted structures can be impossible to register, difficult to insure, and problematic to resell. Maris Estates insists on a clean engineer's report as a standard part of the process, protecting both your legal title and the future liquidity of your investment.
Greece has a capital gains tax on the sale of real estate by individuals set at a rate of 15 percent on the profit. However, the application of this tax has been suspended for many years through successive extensions, and the suspension currently runs to the end of December 2026. During the suspension, gains realised on the resale of property by individuals are not taxed.
This suspension has been a meaningful advantage for investors focused on capital appreciation, since it allows gains from rising values to be realised without a capital gains charge under the current framework. The suspension is reviewed and extended periodically, so the position beyond its current expiry should be confirmed at the time of any future sale.
Sellers should still account for other resale-related costs and for how the property was originally acquired and declared. Maris Estates advises clients on exit strategy and timing as part of long-term planning, and works with tax counsel to ensure the disposal is structured efficiently under the rules in force when you sell.
For a straightforward cash purchase of a resale property, the typical timeline from accepted offer to registered ownership is around six to twelve weeks. The main variables are how quickly the AFM and bank account are arranged, the completeness of the seller's documentation, and the time needed for legal and technical due diligence, which should never be rushed.
Certain situations extend the timeline. Financed purchases add several weeks for the bank's valuation and loan approval. Properties in border zones requiring non-EU permits, complex inheritance chains, or planning matters that need regularisation all take longer. Off-plan new-builds follow the developer's construction schedule with staged payments.
Careful preparation is the best way to keep to schedule: securing the AFM early, having funds ready in a compliant account, and instructing an experienced lawyer at the outset. Maris Estates project-manages these moving parts so the purchase proceeds as efficiently as the specific property allows.
Yes. It is common and entirely standard for foreign buyers to complete a Greek purchase without travelling, by granting a power of attorney (PoA) to a trusted Greek lawyer. The PoA authorises your representative to obtain your AFM, open a bank account, sign the preliminary agreement and, where you wish, execute the final deed before the notary on your behalf.
The power of attorney must be properly formalised to be valid in Greece. It is typically signed before a Greek consulate abroad, or before a local notary in your home country with an apostille and an official Greek translation. The document should define the representative's authority precisely, so it covers each required act while giving you appropriate control.
This mechanism makes cross-border investment genuinely convenient, and it is one reason international buyers find Greece accessible. Maris Estates works alongside your lawyer to prepare a correctly scoped PoA and coordinate the remote signing, so you can acquire and register your property securely from anywhere in the world.
Greek property passes under Greek inheritance rules, and inheritance tax is levied according to the relationship between the deceased and the beneficiary. Beneficiaries are grouped into categories, with the closest family, such as spouses, children and parents, in Category A taxed most favourably, and more distant relatives and unrelated heirs taxed at progressively higher rates in Categories B and C.
For close family in Category A, generous tax-free thresholds apply and rates on amounts above them are comparatively low, so a family home passing to a spouse or child often attracts modest tax. Rates rise for Category B and reach the highest bands for unrelated beneficiaries in Category C, where the effective cost can be significant.
Because succession planning across borders can be complex, and because a beneficiary must accept the inheritance and register the transfer with the notary and Cadastre, it is wise to plan ownership structure with these outcomes in mind. Maris Estates can introduce specialist estate and tax counsel so that your Greek asset is held and, in time, transferred in a way that suits your family's long-term intentions.
Both offer compelling opportunities, and the decision comes down to lifestyle, liquidity and the character of the investment. The most established islands, such as Mykonos, Santorini, Paros and parts of the Cyclades, command premium prices, strong international demand and resilient values, but they also sit within the highest Golden Visa threshold band and can involve more seasonal access.
The mainland coastline, including the Athenian Riviera, the Peloponnese and Halkidiki, offers year-round accessibility, proximity to international airports and infrastructure, and, outside the top-tier zones, often a lower entry threshold for residency purposes. These areas have attracted significant regeneration and can offer attractive relative value alongside strong appreciation prospects.
For capital-appreciation investors, the enduring principles are location quality, ease of access, scarcity of comparable stock and clean title. Maris Estates advises clients across both islands and mainland, matching the choice to their objectives, whether that is a trophy island asset or a well-connected coastal property with strong long-term fundamentals.
The Golden Visa grants residency, not citizenship. A residence permit gives you and your family the right to live in Greece and travel within the Schengen Area, renewable every five years for as long as you hold the qualifying investment, but it does not confer a Greek or EU passport, and it carries no obligation to actually reside in the country.
Greek citizenship is a separate and far longer path. It is generally acquired through naturalisation after a sustained period of lawful residence, typically several years of genuine physical presence, along with integration requirements such as knowledge of the Greek language and culture. Time spent purely as a non-resident Golden Visa holder does not on its own build toward naturalisation, because that route depends on real residence.
For most international investors, permanent renewable residency through the Golden Visa achieves the practical goals of mobility, an EU base and a secure asset, without the commitment naturalisation requires. Maris Estates focuses on the investment and residency side and can direct clients to immigration counsel where citizenship is a genuine long-term objective.
Greece is part of the Eurozone, so property is priced, taxed and transacted in euros (EUR). Membership of the euro brings stability and removes any local-currency devaluation risk from your investment, which is an important consideration for international buyers comparing Greece with markets that use volatile local currencies.
Purchase funds are generally transferred into a Greek bank account in the buyer's name and then paid to the seller through the transaction, which also creates the clean paper trail required for the notarial deed, for anti-money-laundering compliance, and, where relevant, for evidencing a Golden Visa investment. Banks will ask for documentation on the source of funds, so this should be prepared in advance.
Because exchange-rate movements between your home currency and the euro can materially affect the effective cost, many buyers use a specialist foreign-exchange provider to secure competitive rates and, in some cases, to fix a rate ahead of completion. Maris Estates can point clients to reputable banking and currency partners so that funding the purchase is smooth, compliant and cost-effective.
Yes. The United States places no citizenship or residency requirement on real-estate ownership. A foreign national who has never set foot in the country can hold legal title to a home, condominium, or piece of land exactly the same way a US citizen can, and there is no federal registry that restricts, taxes, or limits ownership on the basis of nationality. Foreign buyers purchased roughly 78,100 US homes worth about 56 billion dollars in the twelve months ending March 2025, a 44 percent jump over the prior year, so international ownership is both common and well understood by every professional in the transaction chain.
There are a small number of narrow exceptions worth knowing about. A handful of states have recently passed laws restricting purchases near military bases or agricultural land by buyers from a specific list of countries, and certain federal rules can apply to land adjacent to sensitive installations. These measures affect a tiny fraction of transactions and almost never touch ordinary residential or investment property in the metropolitan markets international buyers favor. For the vast majority of purchases, your nationality is simply not a factor.
What buying does not do is grant you any immigration status. Owning a US home gives you no visa, no right to live in the country, and no path to a green card on its own. It is purely an ownership and investment decision. At Maris Estates we make sure clients understand that distinction from the outset so that the property strategy and any separate immigration strategy are planned independently and correctly.
Foreign nationals can finance a US purchase, but not usually through the conventional agency loans available to citizens. Instead, a specialized product known as a foreign-national mortgage is offered by portfolio lenders, private banks, and some international banks. These loans are designed for buyers who have no Social Security number, no US credit history, and income earned abroad, and they are underwritten against the property and the borrower's global financial profile rather than a US credit score.
The defining feature is a larger down payment. Where a resident might put down 20 percent or less, a true non-resident buyer should plan for roughly 30 to 40 percent down, with the exact figure depending on the lender, the property type, and the buyer's country and profile. Green-card holders and buyers on qualifying work visas can sometimes access far lower down payments, and buyers using an ITIN in place of a Social Security number may find programs starting around 15 to 25 percent. Note that as of May 2025 FHA-insured loans are no longer available to non-permanent residents, which pushes most foreign buyers toward portfolio and private-bank financing.
Documentation is straightforward but international in nature: a valid passport, proof of income from foreign employment, business, or investments, several months of bank statements, evidence of reserves, and funds held in or transferred to a US account for the down payment and closing. Because rates and terms vary widely between lenders, Maris Estates recommends securing a written pre-approval before making offers, so that your budget and your negotiating position are both defined with confidence.
A large share of foreign buyers pay all cash, and there are good reasons for it. An all-cash offer is simpler, faster, and more attractive to sellers because it removes financing contingencies and the risk of a loan falling through. In competitive markets a clean cash offer can win a property over a higher bid that depends on a mortgage, and it eliminates the higher interest rates and heavier documentation that foreign-national loans typically carry.
Financing, however, is not merely a way to buy something you cannot otherwise afford. Using a mortgage lets you deploy less capital into a single asset and preserve liquidity for other opportunities, and in some circumstances the interest can have tax planning value. For buyers whose home currency is strong against the dollar, or who prefer to keep investment capital diversified rather than concentrated, a moderate loan can be a deliberate strategy rather than a necessity.
The right answer depends on your goals, your cost of capital at home, and your view on US interest rates and the dollar. Maris Estates helps clients model both paths side by side, weighing the certainty and speed of cash against the flexibility and leverage of financing, so the decision reflects an overall investment plan rather than a default assumption.
An ITIN, or Individual Taxpayer Identification Number, is a tax processing number issued by the Internal Revenue Service to people who have US tax obligations but are not eligible for a Social Security number. Foreign property owners frequently need one because it is how the IRS identifies you when you file returns, claim treaty benefits, or reclaim tax that has been withheld from you. You do not need an ITIN simply to hold title, but you will almost certainly need one once you interact with the US tax system as an owner or seller.
You apply using IRS Form W-7, submitting it with certified identity documents such as a passport. Standard processing generally takes around seven to eleven weeks, so it pays to start early. In the specific situation of a foreign owner selling and seeking to reduce withholding, the W-7 can be filed together with the related withholding forms, which can shorten processing considerably. Many buyers obtain the number well ahead of any sale precisely to avoid delays later.
Because the ITIN touches financing, tax filing, and the eventual resale of your property, Maris Estates coordinates with a qualified cross-border accountant to get the application right the first time. A rejected or delayed ITIN can hold up a closing or tie up sale proceeds, so treating it as an early, deliberate step rather than a last-minute formality protects both your timeline and your funds.
FIRPTA, the Foreign Investment in Real Property Tax Act, is the mechanism the US uses to make sure foreign sellers pay any tax owed on the gain from selling US real estate. When a foreign person sells, the buyer is legally required to withhold a percentage of the gross sale price and remit it to the IRS, generally within 20 days of closing. In practice the title or escrow company handles this at closing so the buyer meets the obligation automatically.
The standard withholding rate is 15 percent of the total amount realized. Two reduced tiers exist when the buyer intends to use the property as a residence: the rate drops to 10 percent when the sale price is between 300,001 and 1,000,000 dollars, and to zero when the price is 300,000 dollars or less. Prices above one million dollars are withheld at the full 15 percent. It is important to understand that this is withholding on the sale price, not a final tax bill.
Because the withholding is based on gross proceeds rather than actual profit, it very often exceeds the tax truly owed. A foreign seller recovers the difference by filing a US tax return, or can apply in advance for a withholding certificate on Form 8288-B to have the IRS approve a reduced amount before closing, in which case the excess is held in escrow until the IRS responds. Maris Estates plans for FIRPTA from the moment a client considers selling, coordinating the certificate application and the ITIN so that as little capital as possible is tied up unnecessarily.
Property tax in the United States is levied locally, by counties, cities, and school districts, and it is charged every year based on the assessed value of your property. There is no single national rate. Instead, effective rates vary enormously from place to place, ranging from well under 1 percent of value per year in some low-tax states to well over 2 percent in others, so an identical purchase price can carry very different annual carrying costs depending on where the property sits.
States with no state income tax, such as Florida and Texas, often recover revenue through higher property taxes, while other states balance the two differently. The tax is reassessed periodically and can rise as local values increase, so the figure you pay in your first year is not fixed for the life of ownership. Some jurisdictions offer caps or homestead relief, though those benefits are typically tied to primary residence and may not apply to a foreign owner's second home or investment property.
Because property tax is a recurring cost that materially affects net returns, Maris Estates always presents clients with the specific annual figure for a given property and county rather than a national average. Understanding the true carrying cost up front, alongside insurance and any association dues, ensures that the investment case is built on real numbers rather than a rough estimate.
Closing costs are the collection of fees and charges that fall due at the moment ownership transfers, on top of the purchase price itself. They typically include title insurance, escrow or settlement fees, recording fees, transfer taxes in some jurisdictions, attorney fees where a lawyer is used, and, if you are financing, lender-related charges such as an appraisal and loan origination. International buyers should generally budget an additional 2 to 5 percent of the purchase price to cover them.
The exact total varies significantly by state and by whether you are paying cash or borrowing. Some states impose meaningful transfer or documentary taxes; others do not. Cash buyers avoid all lender-related costs, which can trim the figure noticeably. Who customarily pays which fee, buyer or seller, also differs by region and is often a point that can be negotiated within the purchase contract.
Maris Estates provides clients with an itemized estimate of closing costs early in the process, well before the closing date, so there are no surprises when the final settlement statement arrives. Knowing the all-in cost of acquisition, purchase price plus closing costs, lets you compare properties accurately and plan your currency transfers with the right amount in hand.
Title insurance and escrow are two pillars of the American closing system that give foreign buyers a great deal of protection. Escrow refers to a neutral third party, typically a title or settlement company, that holds the funds and documents during the transaction and releases them only when every condition of the contract has been satisfied. This means your money is never handed directly to the seller on trust; it moves only when the deal is verified and complete.
Title insurance protects your ownership itself. Before closing, the title company researches the property's history to confirm the seller truly owns it and that there are no undisclosed liens, unpaid taxes, or competing claims. The insurance policy then protects you financially if a defect in that history surfaces later. A one-time premium paid at closing covers you for as long as you own the property, which is especially reassuring for a buyer who is not physically present to investigate a property's local history.
For international clients, this system is one of the reasons US real estate is considered a secure place to hold wealth. Maris Estates works only with reputable title and escrow companies and reviews the title commitment carefully on your behalf, so that the property you pay for is genuinely, cleanly, and permanently yours.
Many foreign buyers hold US property through a limited liability company, or LLC, rather than in their personal name, and there are several reasons it can make sense. An LLC creates a layer of liability separation between the asset and your personal wealth, offers a degree of privacy since the individual owner's name need not appear on the public deed, and can simplify how the property is transferred or eventually passed to heirs. For buyers acquiring more than one property, an LLC structure can also keep holdings organized.
Ownership structure also interacts heavily with US tax exposure, particularly estate tax. Depending on how a structure is arranged, whether the property is held directly, through a US LLC, or through a foreign corporation or blocker entity, the exposure to US estate tax, capital-gains tax, and reporting obligations can differ substantially. There is no single structure that is best for everyone; the right choice depends on your country of residence, whether a tax treaty applies, the value of the asset, and your long-term intentions.
Because these decisions are difficult to unwind once a purchase is complete, Maris Estates coordinates with cross-border tax and legal advisors to settle the ownership structure before you go under contract. Getting it right at the outset can protect both the asset and the next generation, whereas restructuring later can be costly and sometimes triggers tax.
No. This is one of the most common and most important misunderstandings among international buyers. Purchasing real estate in the United States, at any price, does not grant you a visa, the right to live in the country, work authorization, or a path to a green card. Ownership and immigration are governed by entirely separate systems, and the US does not offer a residency-by-property-purchase program the way some other countries do.
As a foreign owner you can generally visit your property under whatever visa or visa-waiver arrangement already applies to your nationality, the same terms as any other visitor, and those terms limit how long you may stay. Owning a home does not extend that permitted stay or change your status in any way. If living in the US is part of your plan, that has to be pursued through a proper immigration route.
There is one program where a large investment can lead to residency, the EB-5 Immigrant Investor Program, but it is an investment-and-job-creation program, not a real-estate purchase, and it has its own strict requirements and thresholds. It should never be confused with simply buying a home. Maris Estates keeps the property strategy and any immigration strategy clearly separate, and refers clients to qualified immigration counsel where residency is a genuine objective.
The US purchase process is well defined and moves through predictable stages. It begins with defining your goals and budget and, if you are financing, obtaining a written mortgage pre-approval. Your advisor then identifies and shows suitable properties, you make a written offer, and once buyer and seller agree on price and terms you enter a binding purchase contract accompanied by an earnest-money deposit held in escrow.
After the contract is signed comes the due-diligence period. During this window you complete a home inspection, the lender orders an appraisal if you are borrowing, and the title company researches and insures the title. Contingencies in the contract let you renegotiate or withdraw if the inspection, appraisal, or title turns up problems. Once these steps clear, the transaction proceeds to closing, where funds and signed documents are exchanged and ownership legally transfers to you.
A cash purchase can close in as little as two to three weeks, while a financed purchase more commonly takes around 30 to 45 days from accepted offer to closing, driven largely by the lender's timeline. Being organized with funds, documents, and any ITIN in advance keeps things moving. Maris Estates manages this timeline end to end and, for clients abroad, arranges remote signing so that distance never becomes an obstacle.
Real-estate commissions in the US changed meaningfully following a national legal settlement involving the National Association of Realtors, with new practice rules taking effect on August 17, 2024. Historically, a seller typically paid a total commission that was split between the listing agent and the buyer's agent, and the buyer's agent compensation was advertised on the shared listing service. Under the new rules, offers of buyer-agent compensation can no longer be published on the Multiple Listing Service, and it can no longer be assumed that the seller will automatically cover the buyer's agent.
There is now a second, equally important change aimed at buyers. Before touring homes, a buyer working with an agent must sign a written buyer-representation agreement that spells out exactly how that agent will be paid and states clearly that commissions are fully negotiable and not set by law. In practice, buyer-agent compensation is now negotiated openly, it may be paid by the seller, by the buyer, or shared, and it is settled explicitly rather than assumed. Early market data showed typical buyer-agent commissions beginning to edge down as a result.
For international clients this simply means more transparency, and it makes trusted representation more valuable, not less. Maris Estates explains the compensation arrangement in writing up front, negotiates it as part of the overall deal, and makes sure a foreign buyer is never caught unaware by a fee. Clear, agreed terms protect you and keep your total acquisition cost fully predictable.
Earnest money is a good-faith deposit a buyer submits shortly after an offer is accepted, signaling that the commitment to purchase is serious. It is typically 1 to 3 percent of the purchase price, though in competitive markets it can be higher, and it is not paid to the seller directly. Instead it is held by a neutral escrow or title company and later credited toward your down payment and closing costs at closing.
Whether it is refundable depends on the contingencies written into your contract. Standard contracts include periods for inspection, appraisal, and financing during which you can withdraw and recover your deposit if a genuine problem arises or a condition is not met. If, however, you simply change your mind after those contingency deadlines pass, you generally forfeit the earnest money to the seller as compensation for taking the property off the market.
The practical lesson is that contingencies are your protection, and the deadlines within them matter. Maris Estates structures offers so that a foreign buyer has appropriate, clearly worded contingencies and understands each deadline, ensuring your deposit stays protected while still keeping your offer competitive in the seller's eyes.
A home inspection is a detailed examination of a property's physical condition carried out by a licensed inspector, usually during the due-diligence window after your offer is accepted. It covers the structure, roof, foundation, electrical and plumbing systems, heating and cooling, and other components, and it produces a written report. While an inspection is not legally required, it is strongly advisable, and it is especially valuable for an overseas buyer who cannot personally walk the property. The findings can be grounds to renegotiate the price, request repairs, or withdraw under an inspection contingency.
An appraisal is different in purpose. It is an independent valuation of the property, ordered by the lender when you are financing, to confirm that the home is worth at least what you have agreed to pay. It protects the lender, and by extension you, from overpaying relative to the market. If an appraisal comes in below the contract price, it can open a renegotiation or, under an appraisal contingency, allow you to step back. Cash buyers are not required to obtain an appraisal but many commission one anyway for peace of mind.
Together, the inspection and appraisal are how a remote buyer gains objective, professional confirmation of both the condition and the value of an asset they may be buying sight unseen. Maris Estates arranges reputable inspectors and appraisers, reviews the reports on your behalf, and translates the findings into clear guidance so you can decide with full information.
When a foreign owner sells US real estate at a profit, that gain is subject to US capital-gains tax. If you have held the property for more than one year, the gain is treated as long-term and taxed at the more favorable long-term federal rates; property held for a year or less is taxed at higher short-term rates. The taxable gain is the sale price less your original purchase price and less qualifying costs and capital improvements, so good record-keeping directly reduces the tax you owe.
This is where FIRPTA and capital-gains tax connect. The FIRPTA amount withheld at closing is not the final tax; it is a prepayment against the actual capital-gains liability. After the sale you file a US tax return that calculates the real tax on your net gain, and because withholding is based on gross proceeds it frequently exceeds what is genuinely owed, generating a refund. State-level tax may also apply depending on where the property is located.
Because the interaction of withholding, federal capital-gains tax, any state tax, and possible treaty relief can be intricate, Maris Estates coordinates with cross-border tax advisors well before a sale. Planning the holding period, documenting the cost basis and improvements, and, where appropriate, pursuing a withholding certificate all work together to keep more of your appreciation in your hands.
This is one of the most overlooked risks for international buyers, and it can be significant. US-located real estate is unambiguously a US-situated asset, which means it falls within the US estate tax system regardless of where the owner lives or holds citizenship. If a foreign owner dies while holding the property directly, their estate can face US estate tax on its value.
The exposure is sharp because non-resident aliens receive an estate tax exemption of only 60,000 dollars, in stark contrast to the multi-million-dollar exemption available to US citizens and domiciliaries. Value above that threshold can be taxed at rates climbing to 40 percent, and the estate may be required to file a US estate tax return, Form 706-NA. For a property worth several hundred thousand dollars or more, the potential liability is far from trivial.
Some relief exists. A limited number of countries have estate tax treaties with the US that can enlarge the available exemption, though most nationalities are not covered, and certain ownership structures can change the exposure entirely. This is precisely why ownership structure should be settled before purchase. Maris Estates raises estate tax at the very start and works with cross-border advisors so that a straightforward property purchase does not quietly become a heavy burden on your heirs.
Many US condominiums, townhomes, and planned communities are governed by a homeowners association, commonly called an HOA. If your property is part of one, you pay a recurring fee, monthly or quarterly, that funds shared services and amenities such as building maintenance, landscaping, security, pools, elevators, insurance on common areas, and reserves for major future repairs. These fees are a real and ongoing cost of ownership and vary widely, from modest sums to substantial amounts in amenity-rich buildings.
Beyond fees, an HOA also sets rules that owners must follow, covering matters like exterior appearance, renovations, use of common areas, and community conduct. Associations occasionally levy special assessments, one-time charges to cover a large unexpected expense such as a roof or structural repair, which can be significant and should be understood before buying. Reviewing the association's financial health, reserves, and recent assessment history is an essential part of due diligence.
For an international buyer, HOA dues directly affect the net economics of holding the property and its eventual resale appeal, since buyers scrutinize fees and the financial condition of the association. Maris Estates examines the HOA documents, budget, and rules during due diligence and factors the dues into the investment picture, so you know the full carrying cost and any restrictions before you commit.
Yes. Buying entirely from abroad is well established, and a large share of international purchases involve buyers who are not physically present at closing. The US transaction infrastructure, escrow, title companies, and remote-notarization options, is built to accommodate signing from another country, so you can complete a purchase without booking a flight for the closing day itself.
In practice, documents can be sent to you electronically or by courier, and signatures are executed either before a local notary abroad, at a US consulate, or through remote online notarization where the parties and rules allow it. Funds are wired into escrow rather than exchanged in person, and the title company coordinates the mechanics so that everything comes together on the closing date exactly as it would for a local buyer. A power of attorney can also be arranged where it simplifies matters.
The key to a smooth mail-away closing is preparation: having your ITIN, banking, currency transfers, and identity documents ready in advance so nothing stalls at the last moment. Maris Estates manages the logistics of a remote closing end to end, coordinating the title company, notarization, and wiring instructions, so that distance is a detail rather than a barrier to owning US property.
Because a US purchase settles in dollars, moving your money into the country and converting it at the right time is a meaningful part of the transaction. Funds are transferred by international wire into the escrow account, and buyers usually need a US bank account to hold the down payment, closing funds, and later the ongoing costs of ownership. Setting up that account and understanding your bank's wiring process early prevents delays when a deposit or closing payment is due.
Currency movements can materially change the real cost of your purchase. Between the day you agree a price and the day you close, exchange-rate shifts can add or subtract a noticeable amount from what you actually pay in your home currency. Specialist foreign-exchange providers frequently offer better rates and lower fees than a standard retail bank, and tools such as forward contracts can lock in a rate in advance to remove uncertainty on a large sum.
Timing your conversion and using the right provider are decisions worth taking seriously on a purchase of this size. Maris Estates helps clients plan the currency side alongside the property side, coordinating with reputable FX specialists and aligning transfers with the closing schedule, so that exchange-rate movements and unnecessary fees do not erode the value of your investment.
International buyers concentrate heavily in a handful of states, with Florida, California, and Texas together accounting for more than half of all foreign purchases in the most recent data. Florida is the clear leader, drawing buyers from across Latin America, Canada, and Europe thanks to its lifestyle, its lack of state income tax, and large, well-established international communities. California ranks second, propelled in part by strong demand from Asian buyers, while Texas draws heavily from Mexico and India.
Beyond the big three, New York and Arizona are consistent favorites, each attracting a distinct mix of nationalities. The top countries of origin for US buyers are China, Canada, Mexico, India, and the United Kingdom, and each tends to cluster in particular regions and metropolitan areas that suit their lifestyle preferences, business ties, and existing communities. These patterns make certain markets especially liquid and familiar for foreign owners at resale.
The best market for you, though, depends on your own objectives, whether you prioritize capital appreciation, a lifestyle base, currency and tax efficiency, or long-term wealth preservation. Popularity signals liquidity and a deep pool of future buyers, which matters for resale, but it does not automatically mean value. Maris Estates advises clients on where their specific goals and the local market dynamics align, rather than simply following the crowd.
For international investors, the core of the return in US real estate comes from capital appreciation, the growth in the property's value over time, realized when you sell. The US has historically been regarded as a stable, transparent, and liquid market in which to hold real assets, backed by strong legal protection of ownership, dependable title insurance, and deep pools of buyers in the major markets. For many foreign investors, US property serves as both a growth asset and a way to hold wealth in dollars.
Choosing the right market and the right property is what drives appreciation. Location, the trajectory of the local economy, supply constraints, and the depth of future buyer demand all shape how much a property gains over a holding period, and buying well, at the right price in the right area, is where much of the eventual return is created. Popular international markets also tend to offer stronger resale liquidity, meaning you can exit more easily and to a wider audience when the time comes.
Realizing that return well requires planning the exit as carefully as the entry, accounting for FIRPTA withholding, capital-gains tax, and any state tax, and timing the sale and the currency conversion thoughtfully. Maris Estates approaches every purchase with the eventual resale in mind, advising on markets and assets positioned for appreciation and structuring the holding so that as much of your gain as possible is preserved when you sell.
A 1031 like-kind exchange is a provision of the US tax code that lets an owner of investment property defer the capital-gains tax normally due on a sale, provided the proceeds are reinvested into another qualifying US investment property within strict timelines. Rather than paying tax on the gain at the point of sale, the tax is postponed and effectively rolled forward into the replacement property, which can allow an investor to reposition or upgrade holdings without an immediate tax cost.
Foreign owners can use a 1031 exchange, but the rules are technical and unforgiving. There are firm deadlines for identifying and closing on the replacement property, the funds must be handled by a qualified intermediary rather than touched by the seller, and the exchange must satisfy specific requirements to qualify. Importantly for foreign sellers, the interaction between a 1031 exchange and FIRPTA withholding needs careful, advance coordination, since the withholding mechanics do not simply disappear because an exchange is planned.
A 1031 exchange is a tool for deferring tax while staying invested in US real estate, and whether it fits depends entirely on your circumstances and long-term intentions. Maris Estates flags the possibility where it is relevant and works alongside qualified tax advisors and intermediaries to structure it correctly, so that a mistimed step does not cost you the deferral you were counting on.